Thai payroll follows a clear monthly rhythm: calculate, withhold, pay, file. But 2026 has changed three things in that rhythm. The social security wage ceiling rose on 1 January. Employee Welfare Fund contributions became payable from 1 October 2026. And electronic filing of PND1 is now the default rather than the option.
Here is the cycle, step by step.
Step 1: Register before the first payroll
Register the company as an employer with the Social Security Office (SSO) and the Revenue Department before running the first payroll. If you employ 10 or more people and do not operate a provident fund, register with the Department of Labour Protection and Welfare for the Employee Welfare Fund through its e-Service system.
Step 2: Collect employee data and allowance declarations
Withholding depends on what each employee is entitled to claim. Collect personal allowances, spouse and child details, insurance premiums and other reliefs at onboarding, and refresh them every year.
Step 3: Calculate gross pay
Gross pay includes salary, overtime, bonuses, allowances and benefits in kind. Employer-provided accommodation and tax paid by the employer on the employee's behalf are assessable income and belong in the calculation.
Step 4: Apply statutory deductions
Social security. Employer and employee each contribute 5% of wages. From 1 January 2026, the wage ceiling is THB 17,500 a month, so the maximum contribution per party is THB 875. The ceiling rises to THB 20,000 in 2029 and THB 23,000 in 2032.
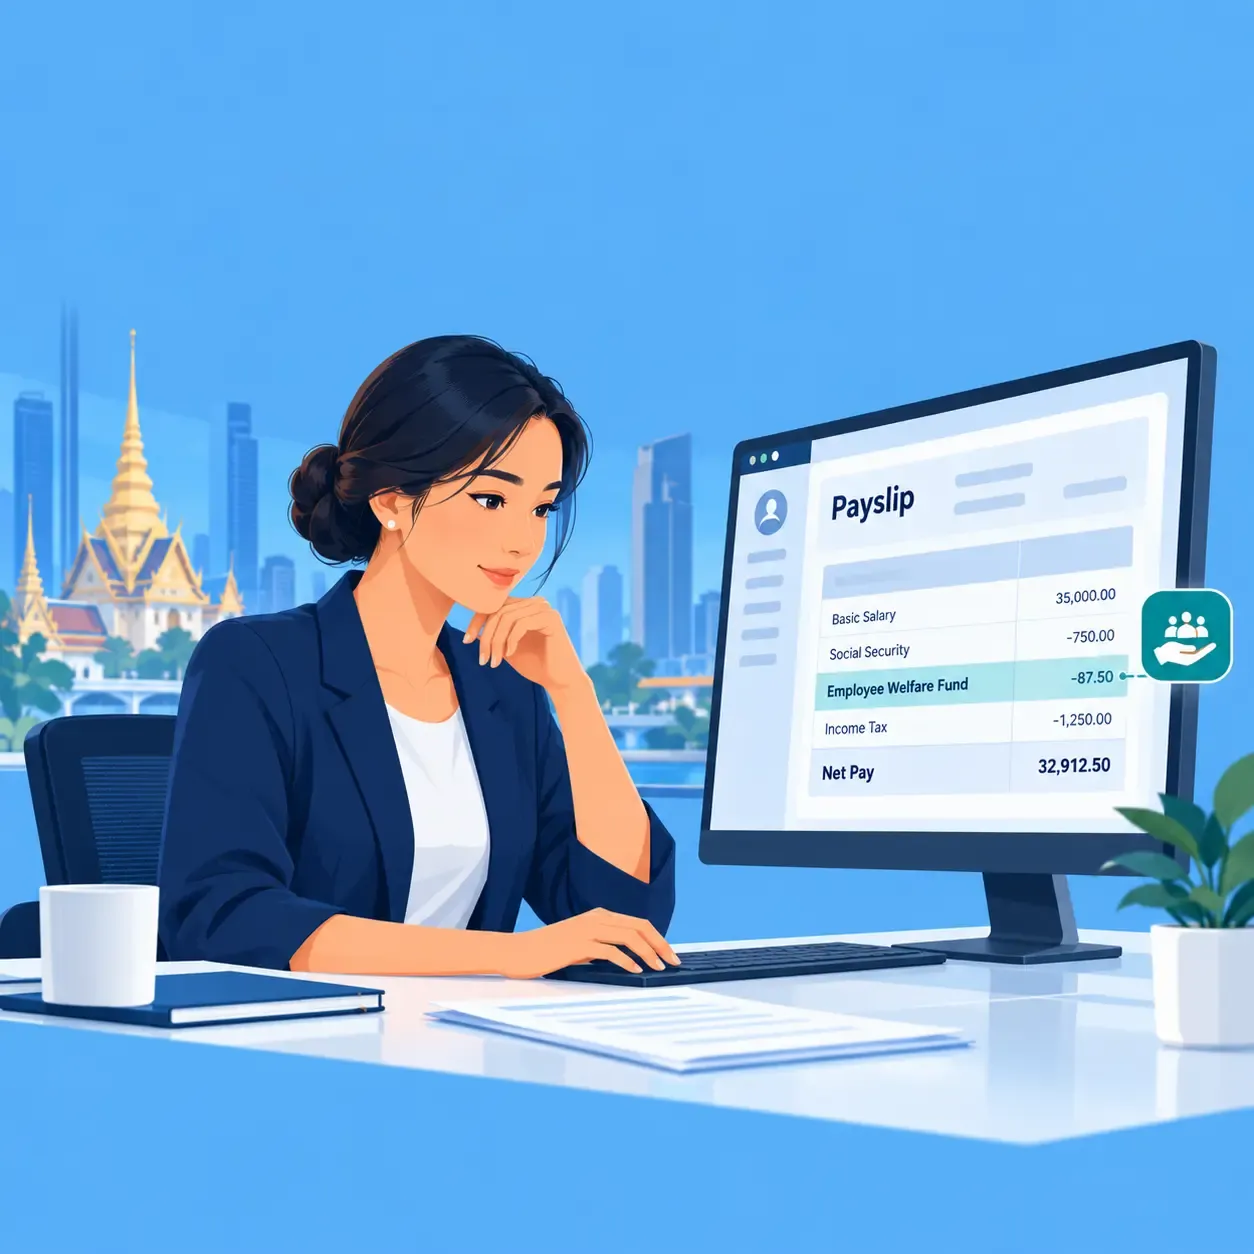
Employee Welfare Fund. From 1 October 2026, employers with 10 or more employees and no provident fund contribute 0.25% of wages, matched by a 0.25% employee deduction. The rate rises to 0.50% each from 1 October 2031.
Provident fund. Where an employer operates one, both sides contribute between 2% and 15% of wages.
Step 5: Calculate personal income tax withholding
There is no flat rate. The employer projects each employee's annual employment income, deducts the 50% employment expense allowance (capped at THB 100,000), applies personal allowances such as the THB 60,000 personal allowance, and calculates tax at progressive rates from 0% to 35%. The result is divided across the remaining pay periods.
Because it is a projection, a bonus or promotion changes the withholding for every remaining month.
Step 6: Pay and issue payslips
Pay net salary and issue payslips that show each deduction clearly. With the Employee Welfare Fund new this year, a short explanation of the new line will save HR many questions.
Step 7: File and remit by the deadline
| Obligation | Deadline |
| PND1 (withholding tax) | 7th of the following month on paper; 15th via e-filing |
| Social security | 15th of the following month |
| Employee Welfare Fund | 15th of the following month |
Under the Revenue Department's Notification No. 451, withholding tax returns are to be e-filed from 1 January 2025. The eight-day e-filing extension applies to filings made up to 31 January 2027, so build a review point into the payroll calendar before then.
Late remittance of tax attracts a surcharge of 1.5% per month or part of a month under Section 27 of the Revenue Code.
Step 8: Close the year
PND1 Kor, the annual reconciliation, is due by 28 February, or 8 March if filed electronically. Each employee needs a Form 50 Tawi withholding certificate by 15 February. Leavers need theirs within one month of their last day.
Step 9: Keep leave and termination in step
Leave, overtime and termination payments all flow through payroll. Thailand's leave rules expanded in December 2025 under the Labour Protection Act (No. 9) B.E. 2568, with 120 days of maternity leave and 15 days of paternity leave. Check that your leave configuration matches before it reaches the pay run.
Where systems help
Thai payroll now carries four monthly statutory calculations, each with its own base and ceiling. MiHCM Enterprise, delivered in Thailand with our partner iOperation, applies all current rules in every run and produces PND1 and SSO files ready for submission.
Frequently Asked Questions
What is the social security contribution in Thailand in 2026?
Employer and employee each contribute 5% of wages, capped at a wage ceiling of THB 17,500 a month from 1 January 2026. The maximum contribution per party is THB 875.
When is PND1 due in Thailand?
By the 7th of the following month for paper filings, or the 15th for filings made through the Revenue Department's e-filing system.
Does the Employee Welfare Fund apply to my company?
It applies to employers with 10 or more employees that do not operate a provident fund. Contributions of 0.25% each from employer and employee began on 1 October 2026.
How is Thai withholding tax calculated?
The employer projects annual employment income, deducts the 50% expense allowance capped at THB 100,000, applies personal allowances, calculates tax at progressive rates and divides the result across the remaining pay periods.
When must Form 50 Tawi be issued?
By 15 February of the following year for current employees, and within one month of the last day of employment for leavers.
Sources
• MiHCM, PND1 filing in Thailand: The employer's guide to monthly withholding tax
• Baker McKenzie, Thailand: Higher wage base for SSF contributions (December 2025)
• KPMG Thailand, Tax News Flash Issue 157 (January 2026)
• Thai PBS, DLPW on the Employee Welfare Fund from 1 October 2026 (in Thai)
• Tilleke & Gibbins, Thailand Postpones Employee Welfare Fund Contributions
• DFDL, Thailand: Amendment of Labour Protection Act on Family-Related Leave